- Stubbuilder
- Nov 4, 2026
GTL Meaning: What Is GTL on Paystub?
You look at your pay stub and notice GTL in it. You don’t even know what it is, don’t remember signing for anything, and its value is very low. Even if you make use of a check stub maker to create pay records, this line is very likely to be misunderstood. We would like to explain the meaning of GTL.
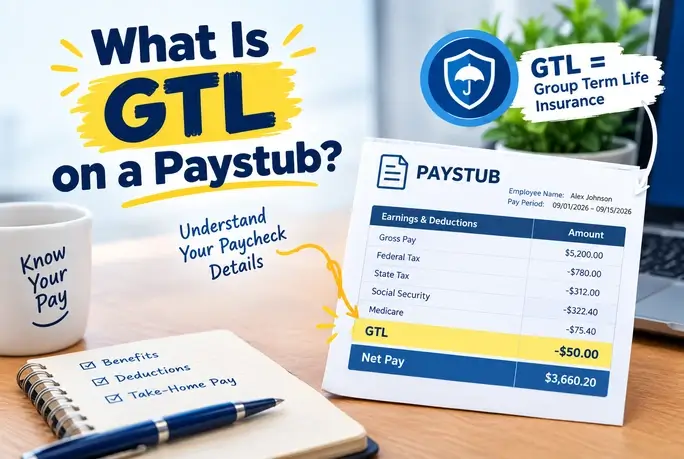
Shortly put, GTL is a group term life insurance. It is an insurance benefit that your employer gives you, and if your coverage is high enough, the IRS will tax the extra coverage, and it becomes your income.
What Does GTL Mean?
GTL- Group term life insurance refers to one insurance policy that treats a large number of employees as one unit. With this type of insurance, if an insured person dies during the period of coverage, the insurer pays the death benefit to the designated beneficiaries.
The policy is popular among employers because it is inexpensive to implement and popular among employees. After all, it is usually not linked to medical tests.
Many employers provide a minimum level of coverage free of charge, which can either be a flat rate figure or a sum corresponding to the employee’s salary. Some of them allow employees to purchase additional insurance.
What Is GTL on a Paycheck?
This is the question that confuses most people, so here it is plainly.
GTL on a paycheck is imputed income, not a deduction and not real cash. Imputed income is the value of a benefit that gets added to your taxable wages even though you never receive that money.
- You don’t get paid the amount.
- It isn’t taken out of your paycheck as a premium.
- It raises the wages used to calculate Social Security and Medicare tax, so your take-home pay may drop by a very small amount.
One exception is worth knowing. If you chose extra coverage and your paystub shows a separate group life line coming out of your pay, that one is a real deduction for supplemental coverage you elected. Quick test: a deduction reduces your net pay directly, while GTL imputed income only increases your taxable wages.
What Is GTL on a Paystub?
According to the mention of GTL on a pay stub, an individual can determine that it is a tax reporting item. It states the reason for the existence of this item.
The Internal Revenue Service (IRS) permits taxpayers to waive the costs related to the first $50,000 base value of the group term life insurance covered by an employer. After calculations are made, if the employees have to pay for insurance with a cost higher than $50,000, the payment for the insurance received will be regarded as a taxable fringe benefit. In such a case, the contribution will be added to the salary and noted in the wage account as GTL.
The attribution of life insurance payment to GTL meaning is the proof of the fact that a life insurance is attributable to the taxable amount.
How Is GTL Taxed?
The procedure for GTL imputed income is as follows:
- For a coverage amount of $50,000 or less, the income remains exempt from tax.
- In case of coverage exceeding $50,000, the coverage exceeding the threshold will be reflected in your compensation received and will be subject to FICA taxes (Social Security and Medicare taxes).
- With regard to the federal income tax, the withholding for such amounts is at the employer’s discretion and is not obligatory.
In the case of spouse and dependent coverage, the rules differ: when your spouse or children are in a separate plan paid for by the employer, the coverage will not be taxed as long as its amount is equal to or lower than $2,000.
One more thing: the GTL calculation includes the amounts of the premium paid from the after-tax income of the insured persons.
The IRS Table Behind GTL Imputed Income
This is an aspect which many people overlook. The taxable figure is not the amount that your employer pays the insurance firm. Instead, it is derived from a uniform premium table created by the IRS that lists a particular monthly fee for each $1,000 of coverage depending on your age group.
| Age | Monthly cost per $1,000 |
| Under 25 | $0.05 |
| 25–29 | $0.06 |
| 30–34 | $0.08 |
| 35–39 | $0.09 |
| 40–44 | $0.10 |
| 45–49 | $0.15 |
| 50–54 | $0.23 |
| 55–59 | $0.43 |
| 60–64 | $0.66 |
| 65–69 | $1.27 |
| 70 and older | $2.06 |
Notice the jumps at 45, 55, and 65. That is why the same coverage creates a bigger GTL line as you get older.
How to Calculate GTL Imputed Income
The formula is simple:
| (Coverage − $50,000) ÷ $1,000 × monthly rate for your age = monthly GTL imputed income |
Multiply by 12 for the yearly total.
- Example 1: 32 years old, $60,000 insurance amount. The excess, which is $10,000, is made up of 10 units of $1,000 each. At a price of $0.08 per unit, this converts to $0.80 per month or $9.60 for the year.
- Example 2: 45 years, $100,000 worth of insurance. Those 50 units are equal to a corresponding excess of $50,000. The monthly cost of excess is $7.50 (0.15 * 50) or $90 annually.
- Example 3: 58 years, $200,000 worth of insurance. There are 150 units corresponding to the excess of $150,000. In this example, we have a monthly cost of $ 64.50 (0.43 per unit) or $774 a year.
Where GTL Appears on Your W2
At the end of the year, GTL imputed income appears on your W2 in two different ways.
- It first appears as part of your total wages in Box 1 (i.e., wages subject to income tax), Box 3 (Social Security subject to tax), and Box 5 (i.e., Medicare taxable wages).
- Second, it will have its own entry in Box 12 with Code C.
Total reported on the December pay stub for GTL income should be in agreement with Box 12, Code C. If you find the numbers are not matching, consult payroll before filing your taxes.
A well-structured pay stub template makes it easier to understand the different sections of a typical pay stub.
Can I Opt Out of GTL?
Typically, group life insurance is a discretionary benefit. Depending on the particular insurance plan, you can often opt out of receiving life insurance during the enrollment period or modify your coverage at the next enrollment period. Some employers automatically enroll employees in the plan, so be sure to confirm this information with your HR representative.
However, it is essential to consider the implications of getting rid of your coverage. By opting out of insurance, you are foregoing coverage that is usually provided without any medical underwriting and for free or at very low cost, in exchange for a small tax savings.
Pros and Cons of Group Term Life
Here are some Pros of GTL:
Pros:
- No cost usually for basic coverage
- No requirement for a medical exam
- Enrollment is easy with your employer
- Extra coverage is offered by many plans
Cons:
- Coverage often stops when you leave
- Taxable value goes up with age
- No cash benefit for coverage
- Family may not have a sufficient amount of coverage by themselves
Final Thought
Ensure that you maintain your payment files in an orderly way so that you can verify your annual totals against your W2 form. If you handle payroll in your business and require accurate payment records, we can help you create pay stubs that are easy to read and properly formatted.
Frequently Asked Questions
1) What does GTL mean in payroll?
GTL is an acronym for Group Term Life insurance. In payroll, this term refers to the taxable cost for any coverage provided by an employer in excess of $50,000.
2) What is GTL imputed income?
This is the amount of coverage that is taxable above the $50,000 limit and will be determined in accordance with the IRS age table and thus added to your wages for tax reporting purposes.
3) Is GTL taxable?
The coverage for the amount up to $50,000 is not. But the excess amount is taxed under Social Security and Medicare taxes.
4) Does GTL reduce my paycheck?
Only slightly affected due to the additional FICA. The GTL amount itself is not deducted from your wages.
5) Why is GTL in payroll showing even though I pay nothing?
The reason for this is the IRS requirement to report the value of coverage above the tax-free limit as income, even in cases when the insurance premium is paid by the employer.